The Real Price of a North Loop Condo Isn't on the Listing
September 24, 2026
September 24, 2026
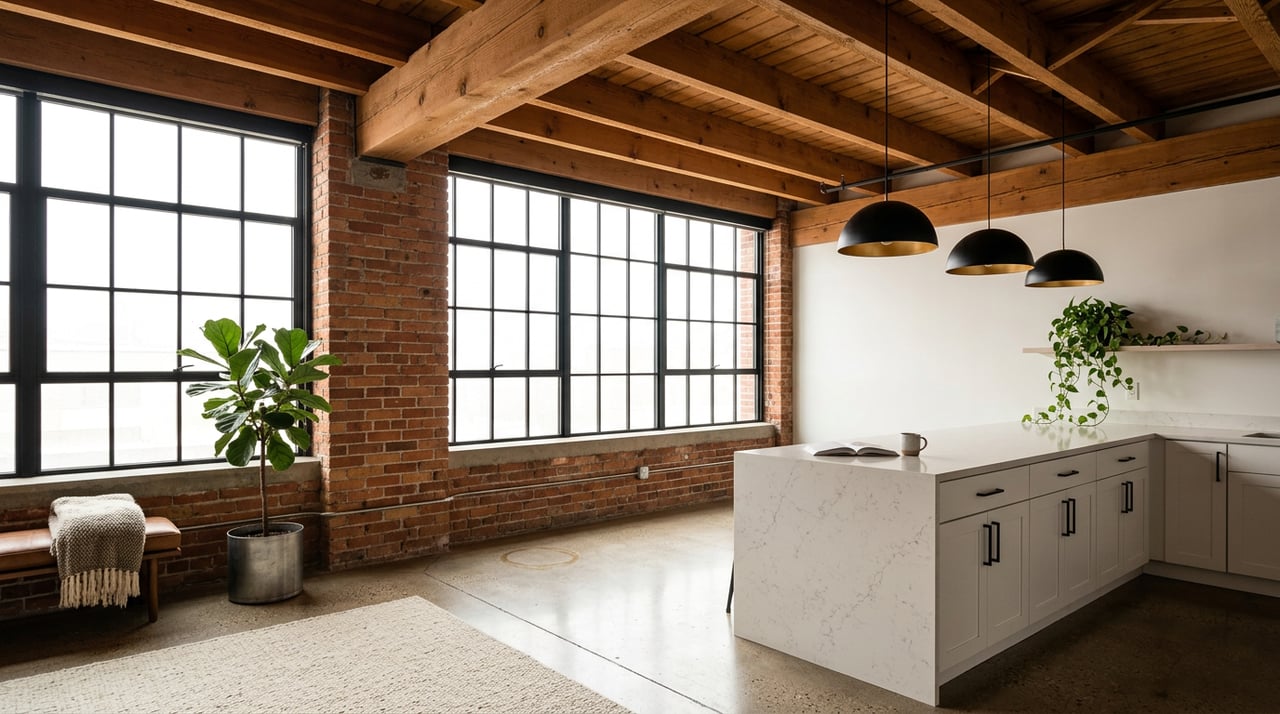
A buyer walks into a corner unit at Herschel Lofts on a Tuesday afternoon. Twelve-foot concrete ceilings, exposed brick, a listing price that feels almost reasonable for a converted 1900s warehouse three blocks from Target Field. Then the agent hands over the HOA sheet, and the number at the bottom changes the math on everything above it.
That moment happens every week in North Loop, and it's the reason the neighborhood's median price is the least useful number a buyer can fixate on right now. Redfin's North Loop condo data from late June 2026 put the median list price at $400,000 across 16 active condos, while other trackers have shown sale prices anywhere from the high $200,000s to the mid $300,000s depending on which months and which buildings get counted. That spread already tells you something: no single price describes this market. What actually determines your monthly cost of ownership, and increasingly what you're legally entitled to see before you sign anything, has nothing to do with the number on the listing sheet.
Almost every condo in North Loop comes with a homeowners association, and the dues run anywhere from roughly $300 to $700 a month depending on the building's age, its amenities, and how it was constructed. That's a wide enough range that two units priced within $20,000 of each other can carry monthly costs that differ by hundreds of dollars, indefinitely.
5th Avenue Lofts, positioned near Target Field with larger floorplans and taller ceilings, has shown HOA dues around $795 a month on recent listings. That's on the higher end for the neighborhood, and it reflects a pattern that shows up across North Loop's building stock: the character that makes these units desirable is often the same feature that makes them more expensive to maintain.
Compare that to a building like 720 Lofts, popular with first-time buyers for its modern finishes and attached heated parking. Newer construction tends to run leaner on base dues, but it frequently unbundles costs that older buildings fold into the monthly fee, most commonly parking and storage. You're not necessarily paying less. You're paying differently, and that distinction only becomes visible once you start comparing total monthly cost instead of list price.
Here's the mechanism buyers keep missing. A converted warehouse like Itasca Lofts, Bookman Lofts, or Security Lofts isn't just older. It has systems that a 2015 mid-rise doesn't: freight elevators built for industrial loads, original windows that predate modern insulation standards, masonry that needs periodic tuckpointing to keep water out of century-old brick. Every one of those components eventually shows up as a reserve line item, and reserve contributions get baked into the monthly HOA fee.
That's the opposite of the assumption most buyers walk in with. They expect the exposed-brick unit with the "authentic" loft feel to be the value play and the glass-and-steel new build to be the premium option. Sometimes the math runs the other way. A well-funded historic association with high dues can be a safer hold than a newer building with low dues and a reserve fund that hasn't been stress-tested against its first major roof or elevator replacement.
The honest version of this trade-off is that you're not choosing between cheap and expensive. You're choosing between paying now, through a higher monthly fee that's already funding future repairs, or paying later, through a special assessment that shows up with much less warning.
This is where North Loop buyers closing in the second half of 2026 are in a genuinely different position than buyers who closed even a year ago, and it's the part of this story that hasn't made it into most condo-buying guides yet.
Minnesota's legislature passed a sweeping rewrite of the law governing condo associations this session, commonly called the HOA Bill of Rights, formally 2026 Minnesota Laws Chapter 82. Governor Walz signed it, and most provisions took effect on May 13, 2026, the day after signing, according to the League of Minnesota Cities' summary of the legislation. A handful of provisions, mostly involving how cities can require HOAs in new developments, don't kick in until January 1, 2027.
For a North Loop buyer, the part that matters most is the change to the resale disclosure certificate, the document a seller's association is required to hand over before you close. Under the amended statute, that certificate now has to include an insurance deductible and loss-assessment warning, a copy of the association's fine schedule and collection policy, and a copy of the reserve study if one exists. You can read the underlying statute directly on the Minnesota Revisor's site if you want to see exactly what the certificate is now required to contain.
That last piece, the reserve study, is the one worth sitting with. Before this year, a buyer touring a converted warehouse building had to ask for that document and hope the association had one, hope it was current, and hope nobody buried a planned assessment in a footnote. Now it's supposed to arrive with the paperwork, as a matter of law, before you're committed to closing.
This doesn't eliminate the risk in an older building's aging systems. It just moves the moment you find out about that risk earlier in the process, which is exactly the kind of change that matters more in a neighborhood built on hundred-year-old brick than it would in a subdivision of five-year-old townhomes.
Here's the piece that should reframe how you read every North Loop listing from now on. Twin Cities condos have become an entry point specifically because of price, and reporting on the metro-wide market has shown HOA fees are a real drag on that entry-level segment, with condos making up the large majority of listings under $200,000 across the region. The units are priced to move. The dues are what decide whether they actually should.
That's the contradiction sitting underneath North Loop's numbers. A building's affordability, measured by the list price alone, can be inversely related to its long-term cost, measured by dues plus assessment risk. The cheapest unit on the block, in the oldest building on the block, with the lowest reserve balance, is often the most expensive place to own five years from now.
None of this requires a lawyer to sort out on your own, but it does require asking for specific documents before you get emotionally attached to a unit. At minimum, request the current reserve study, the last two to three years of the association's financial statements, the assessment history including anything planned or pending, and the owner delinquency rate. A high delinquency rate strains the budget the same way a thin reserve does, just more slowly.
None of these are automatic dealbreakers. A building with lower reserves and a clear multi-year funding plan can be a perfectly reasonable purchase. What changes your risk profile is finding out about the gap before closing instead of after, in the form of a letter announcing a five-figure assessment.
FAQ
Does every condo in North Loop have an HOA? Nearly all of them do. The neighborhood's housing stock is almost entirely multi-family, split between converted warehouses and newer construction, and both types are typically governed by an association under Minnesota's Common Interest Ownership Act.
Does the new disclosure law apply to older buildings, like a warehouse converted in the 1990s? Yes. Minnesota's condo statute applies to condominiums regardless of when the building was created, unlike some planned communities that only fall under the law if they've opted in. If you're buying a unit in a historic conversion, the same resale disclosure requirements apply as they would in a brand new tower.
Is a higher HOA fee always a red flag? No. A high fee paired with strong reserves and a documented funding plan is often the safer building. The red flag is a low fee paired with thin reserves and no clear plan for the freight elevator or the roof when it eventually needs replacing.
If you're weighing a specific North Loop building against another, or trying to read a reserve study you already have in hand, Kary Marpe has spent decades walking Twin Cities buyers through exactly this kind of paperwork before they sign anything. Let's connect, call or email today, before you write the offer, not after.
Stay up to date on the latest real estate trends.
I am always here for personal service by phone or email, so feel free to contact me any time!